

A duration outlook for the belly of October 2026.
I’m becoming more interested in owning duration. But I’m not particularly interested in making the blanket call that “bonds are cheap” and buying whatever has the biggest sensitivity to falling yields.
There are several different bets/trades hiding inside that sentence.
Buying a 2-year Treasury is largely a view on how much more work the Fed has to do. Buying a 5-year is a view on how long restrictive policy can reasonably last. Buying a 30-year means taking those questions and adding much more exposure to fiscal credibility, inflation uncertainty and the compensation investors demand for locking money away.
In Europe, there is another complication. Whose promise are you buying?
My bias for the coming week or so, is selectively constructive on duration, with the strongest preference in the US 3-to-7-year sector. I’m less enthusiastic about extending that view indiscriminately into 30s, and considerably more selective about sovereign exposure in Europe, where we can thank the French!
There is no recession call here, It is a view that parts of the curve can rally without the entire macro story becoming bond-friendly. This idea is key because we don’t need to get every part of the economic outlook right to find a decent rates trade. We do need to understand which part of the outlook our position actually depends on.
Where we are starting
The following yields are as at the end of the past week

At those levels, US 2s10s is 45.1 basis points and 5s30s is 58.0. Germany’s corresponding spreads are 36.5 and 59.4 basis points. The UK is materially steeper beyond the belly, with 5s30s at 95.1 basis points.
France’s 10-year spread to Germany is 137.1 basis points, compared with 109.3 for Italy. France therefore yields 27.8 basis points more than Italy at ten years.
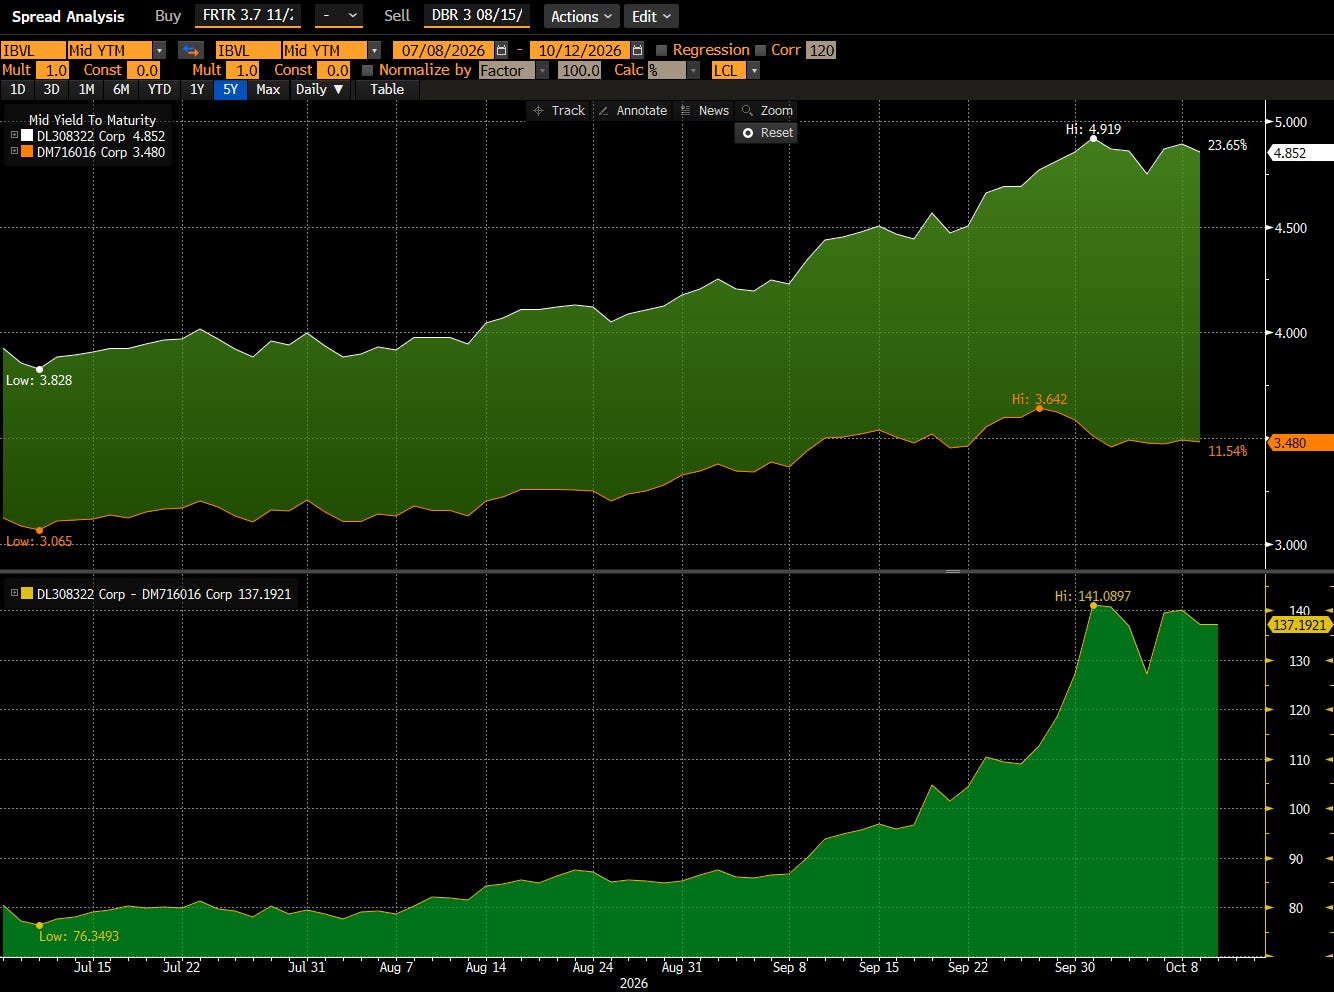
Those are useful starting points, but they are not conclusions. A steep curve does not tell us that it must flatten. A high yield does not establish that a bond is cheap. And a wider sovereign spread is only attractive when the compensation exceeds the risk, rather than merely reflecting it.
Below is a major report of US, GR, FR, UK and IT duration. This is for serious investors or traders. Access with a paid subscription which will come with access to the GMM dashboard site (www.globalmacromethod.com) and discord for a more fluid line of chat etc.
