


US macro outlook for the week of 9–13 November 2026
Friday’s jobs report made life easier for the Fed and more awkward for anyone expecting falling share prices to do the work of weak economic data. The US added 165,000 jobs in October, unemployment slipped to 4.1%, and the previous two months were revised up by 84,000. That gives policymakers something valuable going into this week’s inflation numbers: time.
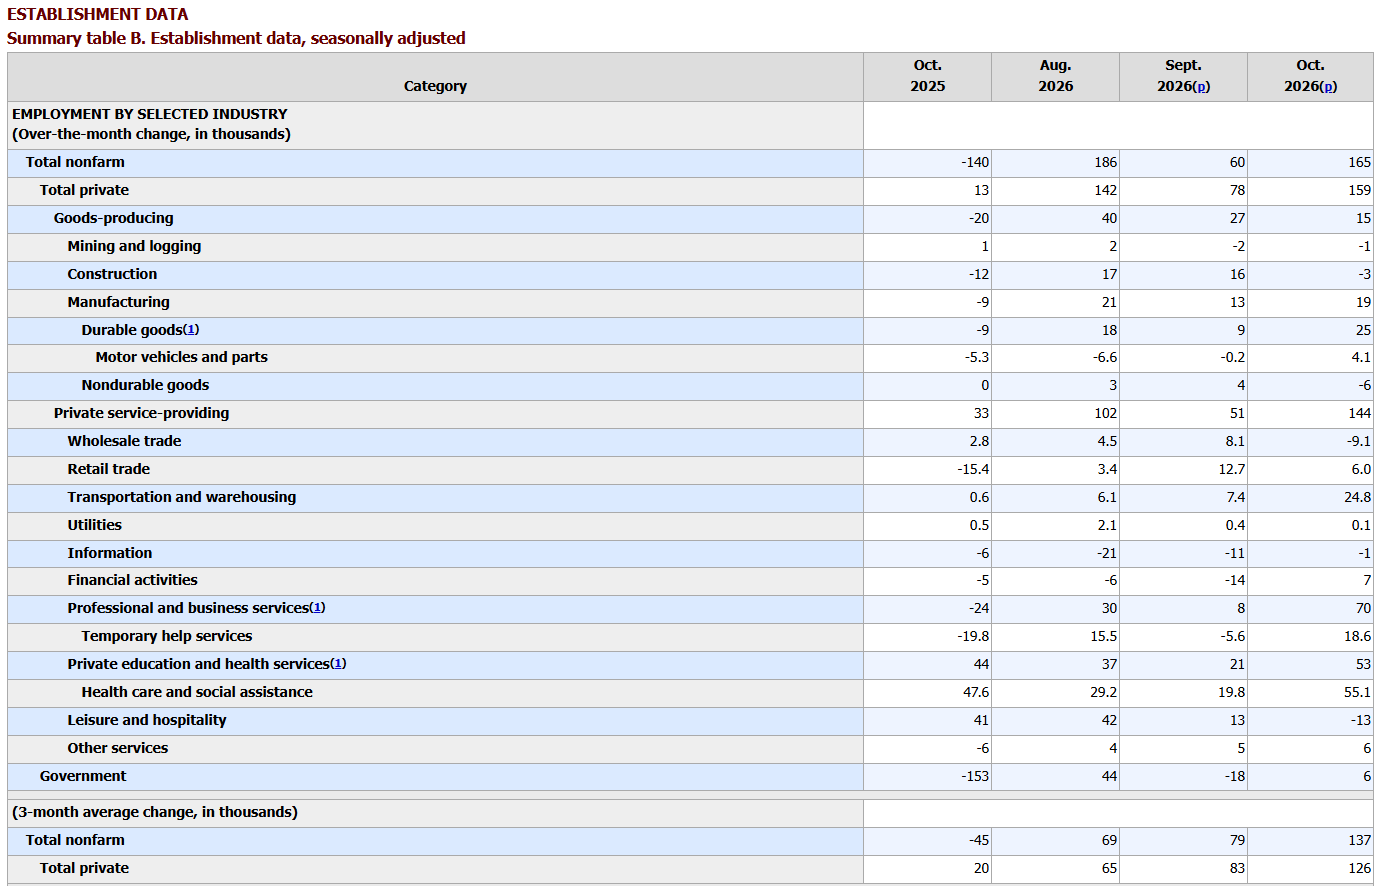
The labour market is giving the Fed the luxury of concentrating on inflation. Meanwhile, the election, the repricing of AI investment and the drop in oil are changing the outlook beyond the next meeting. Those forces can pull rates and equities in different directions. Getting the time horizons right is where I think the opportunity sits.
Below, I’ll work through why strong employment can coexist with a more constructive view on bonds, what would make the technology sell-off matter for the broader economy, and the evidence I want before putting risk on this week.
A paid GMM subscription brings together the research and trade write-ups on Substack, the growing dashboards, and our Discord. I’m also building out the models and educational work around them. If you want to connect the economy, market pricing and actual trades, come and join us.
